HECM Reverse Mortgage

The FHA-insured reverse mortgage for homeowners 62 and older. Turn home equity into cash with no monthly mortgage payments.

Stay in Your Home and
Put Your Equity to Work.

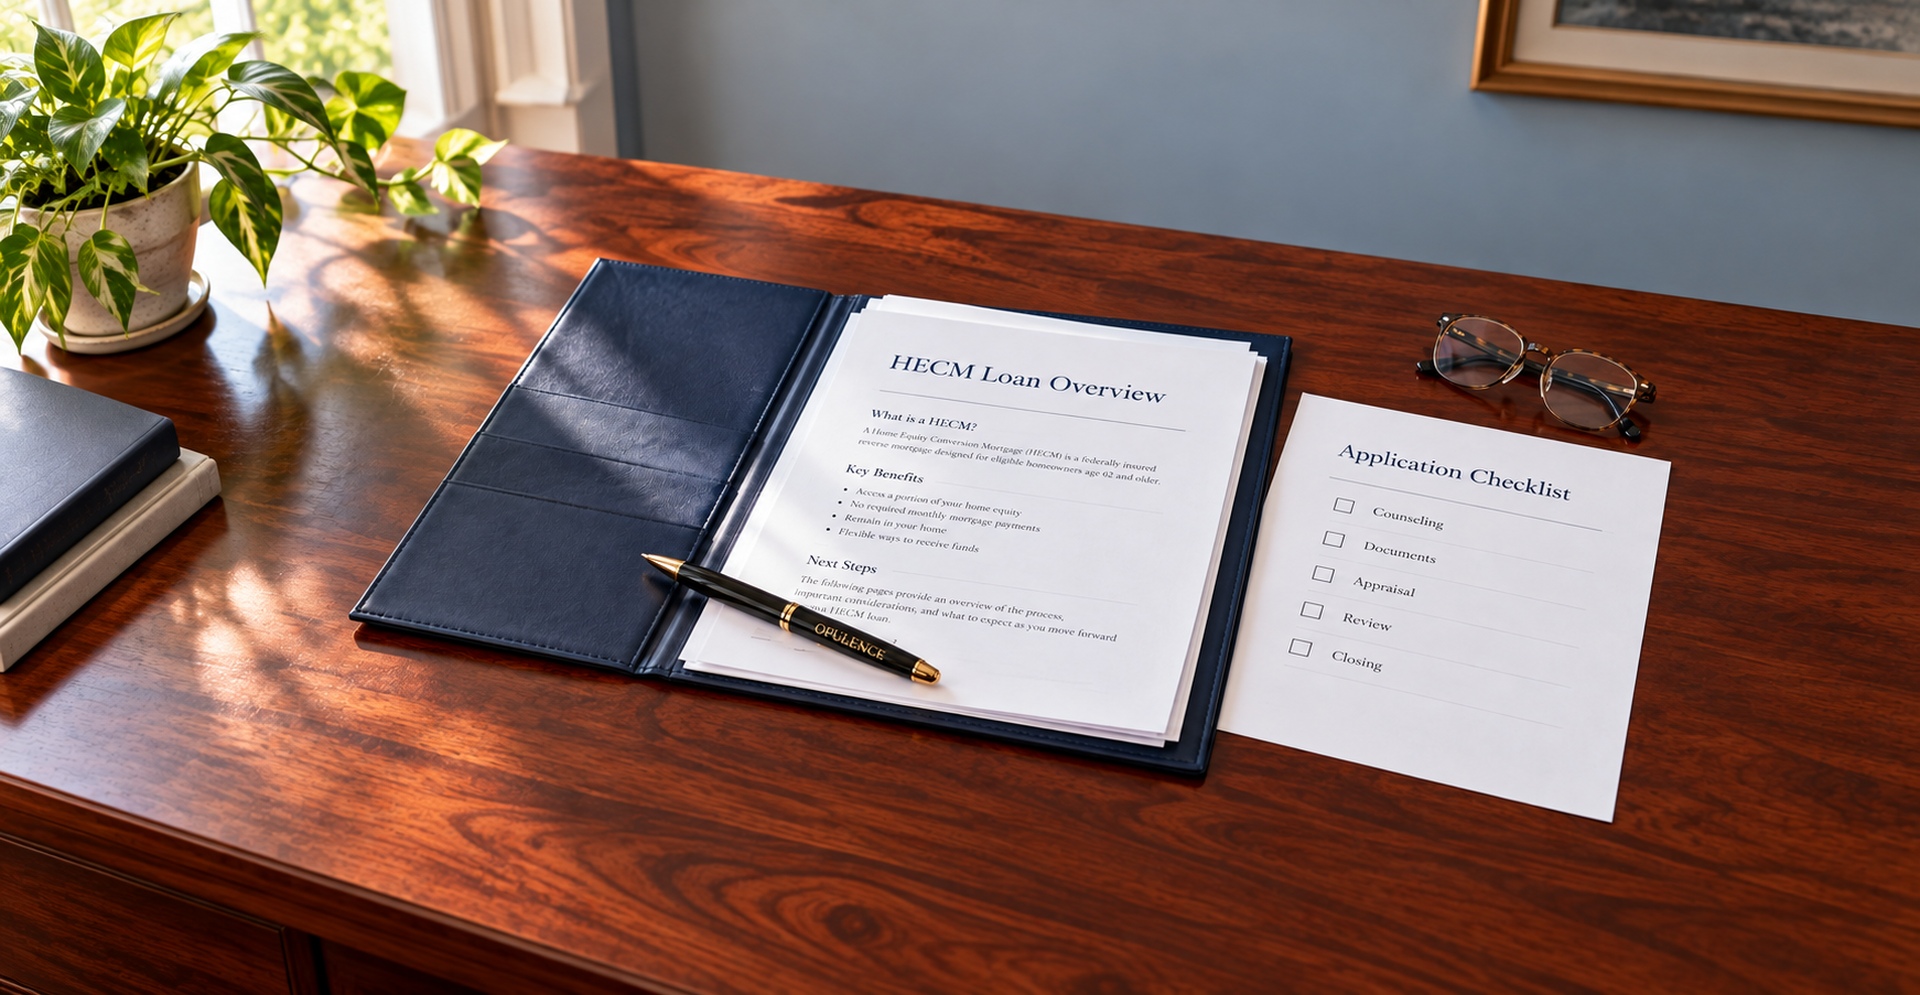
A Home Equity Conversion Mortgage (HECM) lets you convert part of your home’s equity into cash while you keep ownership and live in your home. There are no required monthly mortgage payments, and the loan is insured by the Federal Housing Administration.

No required monthly mortgage payments
Insured by the FHA for added security
A line of credit that grows over time
Non-recourse protection for you and your heirs
Call Us: 800-558-0475

Why Choose a HECM?

The HECM is the most widely used reverse mortgage in the country because it combines federal insurance, strong consumer protections, and flexible ways to receive your money.

Eligibility

Homeowners 62 and older with substantial equity in a primary residence they occupy.

Loan Limits

For 2026, HUD uses home values up to $1,249,125 to calculate how much you can receive.

Payout Options

Take a lump sum, monthly payments, a growing line of credit, or a combination.

Protections

Required independent counseling and non-recourse terms keep the process transparent and safe.

FHA-Insured Security
Federal insurance backs your access to funds and protects you and your heirs from owing more than the home is worth.
Growing Line of Credit
Any unused line of credit grows over time, giving you more available funds in the years ahead.
In-House Processing
From application to closing, your HECM stays with our team. No third-party processors, no handoffs.
The Details

Understanding How
Your HECM Works.

A HECM is a loan, and like any loan it comes with responsibilities. We walk you through every requirement before you apply so there are no surprises after closing.

How Your Equity Is Accessed
The amount available depends on the age of the youngest borrower, current interest rates, and your home's value up to the HUD limit. Any existing mortgage is paid off first, and the remaining funds are yours to use as you choose.
When the Loan Is Repaid
No repayment is due while you live in the home and meet the loan terms. The loan becomes due when the last borrower sells, moves out permanently, or passes away. Heirs can keep the home by repaying the loan or sell it and keep any remaining equity.
Your Ongoing Responsibilities
You keep the title and continue paying property taxes, homeowners insurance, and any HOA dues, and you maintain the home. HUD requires a session with an independent, HUD-approved counselor before you apply, and we help you schedule it.
How It Works

Our Loan Process

Four clear steps from your first conversation to closing day, all handled by one in-house team.

Ready to Get Started?

500 N. Franklin Turnpike, Suite 303
Ramsey, NJ 07446
Call: 800-558-0475
Email: info@ophomeequity.com

    Frequently Asked Questions

    Answers to the questions we hear most about HECM reverse mortgages.

    Who qualifies for a HECM?
    You must be 62 or older, live in the home as your primary residence, and have significant equity. The property must meet FHA standards, and you must complete counseling with a HUD-approved counselor before applying.
    How much money can I receive?
    Your available amount depends on the age of the youngest borrower, current interest rates, and your home's appraised value up to the 2026 HUD limit of $1,249,125. We run your exact numbers at no cost.
    Will I still own my home?
    Yes. You keep the title and ownership of your home. You must continue to live there, pay property taxes and insurance, and maintain the property.
    What happens to my home when I pass away?
    Your heirs can keep the home by paying off the loan, or sell it and keep any equity above the loan balance. Because the HECM is non-recourse, they will never owe more than the home's value.
    Is the money I receive taxable?
    Reverse mortgage proceeds are loan funds, so they are generally not treated as taxable income. Every situation is different, so we recommend confirming with your tax advisor.
    Can I pay off my existing mortgage with a HECM?
    Yes. Many borrowers use a HECM to pay off their current mortgage and eliminate that monthly payment. The existing loan is paid off at closing, and any remaining funds are available to you.
    x

    Contact With Us!

    2220 Plymouth Rd #302, Hopkins, Minnesota(MN), 55305

    Call us: (234) 109-6666

    Mon – Sat: 8.00am – 18.00pm / Holiday : Closed